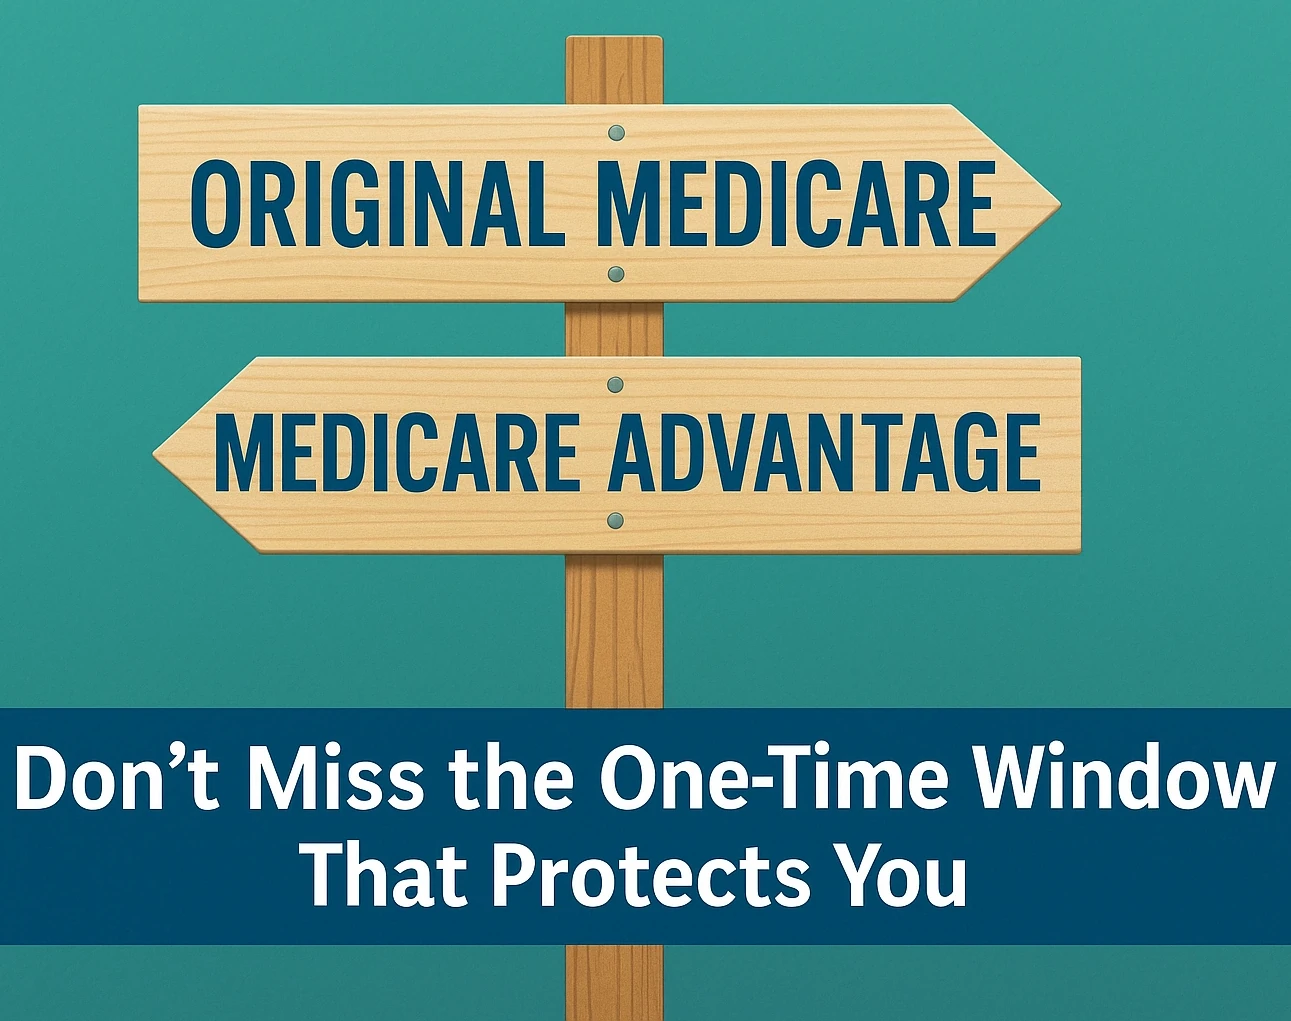
Original Medicare vs Medicare Advantage: Don’t Miss the One-Time Window That Protects You
Learn How to Avoid Costly Coverage Mistakes and Why Timing is Everything After You Turn 65
Learn How to Avoid Costly Coverage Mistakes and Why Timing is Everything After You Turn 65
Learn How to Avoid Costly Coverage Mistakes and Why Timing is Everything After You Turn 65
For many people, when they hear age 65, the first thought might not be: I must decide about health insurance that will likely impact me for the rest of my life. Sure, some might call this hyperbole, and there are certainly many terms that surround Medicare, like Original Medicare, Medicare Advantage, Supplement Insurance (Medigap), and Part D. There’s also the six-month enrollment window and the issue of pre-existing conditions.
While the Affordable Care Act (ACA) addressed pre-existing conditions for primary insurance, it doesn’t apply to secondary private insurance, including those that work in the Medicare Supplement Insurance market. If you apply after the six-month window closes, you may be denied coverage or required to go through medical underwriting.
There is no one-size-fits-all answer, and it can be overwhelming, especially since you only have a six-month open enrollment period that begins the month you turn 65. Our goal is to flag some common pitfalls now, so you and your family won’t regret your choices later.
Although advertisements, especially late-night ones, tout the benefits of Medicare Advantage, it’s important to know that Original Medicare, when paired with Supplement Insurance, can, and often does, provide more comprehensive coverage.
If you want freedom and have the financial resources, then you’re likely looking at Original Medicare. You can see any doctor that accepts Medicare, which is a big plus for those who travel a lot or want to see a specific doctor when they get sick.
But let’s be clear: Original Medicare Part B is full of gaps. Think of it like Swiss cheese. While it covers a lot, there are plenty of holes where you’re left paying out of pocket for things like deductibles, coinsurance, and copays.
That’s why many people add Supplement Insurance, also known as Medigap. It can help fill in many of those holes, so you’re not surprised by big medical bills. Don’t forget, though, you’ll need a separate Part D plan for prescriptions, too.
At first glance, Medicare Advantage can look good on paper. It bundles everything, from prescriptions to dental and vision, but there’s a catch. You’re stuck with a limited network of doctors, and it puts a private insurance company in charge of approving and denying coverage and procedures. And that’s often only after receiving prior authorization.
Yes, the premiums for Medicare Advantage are usually lower than Original Medicare with Supplement Insurance. But out-of-pocket costs for the hospital and ongoing care can be much higher.
Sadly, I’ve seen more and more reports of people on Medicare Advantage being denied services that should have been approved, claims and procedures that would have been automatically covered under Original Medicare.
People need to understand that Supplement Insurance only waives medical underwriting for the first six months after signing up for Medicare Part B. Miss that enrollment window, and you could be stuck paying a lot more, or you might find it harder to qualify later if you have preexisting conditions.
I know one person who missed the six-month window, was applying for Supplement Insurance, and then was diagnosed with breast cancer. Thankfully, they are now in remission, but they’re waiting a few years before reapplying for Supplement Insurance due to concerns about being denied coverage under medical underwriting.
I also know another person who did sign up for Supplement Insurance within the first six months, but when they tried to switch to a different Supplement Insurance plan with the same insurance company in their early 70s, they were denied. Thankfully, they can keep their existing Supplement Insurance plan, but they likely won’t be able to change it.
So even though you might be in great health at age 65, it’s worth thinking ahead. Locking in the Supplement Insurance plan early is often a no-brainer if it fits your budget.
For those just starting out, there are two great resources: the official Medicare website and State Health Insurance Assistance Programs (SHIPs).
This is the official source for all things Medicare. You can find information on plan details, coverage rules, and how and when to enroll. Medicare.gov also provides a tool to search and filter providers for Part D (prescriptions), Supplement Insurance, and Advantage plans.
SHIPs are run by trained volunteers in your state. They’re free, unbiased, and especially helpful. Because there’s no sales pressure, they can help you compare plans and guide you through enrollment timelines.
And honestly, if you’re still confused after reaching out to Medicare and your local SHIP, I suggest speaking with an independent financial advisor who has Medicare expertise and doesn’t receive commissions from the insurance industry. It’s better to get help based on your individual health and financial situation than to end up stuck with a plan that doesn’t fit.
Here’s the hard truth. If you can afford the premiums, Original Medicare with Supplement Insurance often gives you better coverage over the long run. It really matters as your healthcare needs grow with age.
That’s why this six-month enrollment window is so important, since by the time you need it, switching may no longer be possible.
Joseph Gedeon and George Joseph, UnitedHealth faces federal scrutiny into whistleblower claims, The Guardian (June 10, 2025), https://www.theguardian.com/us-news/2025/jun/10/unitedhealth-investigation-whistleblower-nursing-homes.
George Joseph, Revealed: UnitedHealth secretly paid nursing homes to reduce hospital transfers, The Guardian (May 21, 2025), https://www.theguardian.com/us-news/2025/may/21/unitedhealth-nursing-homes-payments-hospital-transfers.
Anna Wilde Mathews, Christopher Weaver, Tom McGinty, The Sickest Patients Are Fleeing Private Medicare Plans—Costing Taxpayers Billions, The Wall Street Journal (Nov. 11, 2024), https://www.wsj.com/health/healthcare/medicare-private-plans-insurers-389af1a0.
Connect with a licensed financial advisor at Woodmont Financial. Schedule a free introductory call today, and let us demonstrate how we’ve assisted others in crafting their retirement.